Irvine, California
We buy good companies, and we keep them.
Stillwater buys founder-owned industrial, B2B and simple service businesses in Southern California. One at a time. There is no fund behind us setting a date to sell, and the people who built the company keep running it.
What Stillwater is
Stewardship, in three commitments.
A company that already works does not need to be redirected. It needs an owner whose job is to protect what makes it work and fund what it needs next. That is the whole idea, and these three commitments are how it is kept.
A permanent home
No fund clock and no pre-set date when someone else decides your company gets sold. The reason that promise is possible is structural, and it is explained in plain language further down this page.
The people stay
Your leadership keeps operating the company. There is no integration playbook, no relocation, and no headcount reduction dressed up as a value-creation plan.
No more than I can own well
Stillwater is not a volume business. How much I buy is set by how much I can genuinely be responsible for, not by a target. What I will not do is take on your company and then be somewhere else.
Where things actually stand
What you should know first.
Three things, before anything else on this page.
- 01I have closed nine acquisitions. Seventeen locations over the last five years, in industrial manufacturing and multi-site services, for private-equity-backed platforms.
- 02Stillwater's first is still ahead. Everything above I did for someone else's balance sheet. Stillwater is the vehicle I built to do it on my own account.
- 03There is no fund behind me. Each acquisition is financed on its own terms — which is an advantage, and the reason why is further down this page.
For owners
Selling the thing you built is not a transaction.
It is the last decision you make about a company you have spent decades on — and most of what you are weighing has nothing to do with the number.
Whether your people keep their jobs. Whether the name over the door survives. Whether the customers you hand-shook with get treated the same way. Whether the buyer disappears three years later and sells you to someone worse.
Those are the right questions, and you should make any buyer answer them before you are in diligence. Here are my answers, in advance.
What does not change
- Your company keeps its name, its brand and its identity.
- Your team stays. I am buying the business because of how it runs, not in spite of it.
- Your location stays. I am not consolidating operations into somewhere cheaper.
- Your leadership keeps operating the company. I am not moving in to run it, and I will not pretend I can do your job better than you did.
- Your customers and suppliers keep the same people on the other end of the phone.
What I commit to
- No fund clock. There is no pre-set date by which I am forced to sell you to someone else.
- No integration playbook. Nothing gets merged into a larger entity or run off a corporate template.
- No headcount reduction as a value-creation plan. If that is the thesis, I am the wrong buyer.
- The price we agree to is the price I work toward. Diligence confirms what you told me — it is not a second negotiation.
- You will know how the deal is financed and who is behind it before you sign anything.
What I buy
A narrow box.
I would rather tell you no than string you along. If a business is outside this, you will hear it on the first call.
- Earnings
- $2M+ EBITDAReal, owner-adjusted, today — not projected. Below that I am not the right buyer.
- Sectors
- Industrial, B2B and simple servicesManufacturing, distribution, industrial and B2B services — and the everyday business you can explain in one sentence: the pest-control route, the janitorial contract, the ferry across the harbor.
- Geography
- Southern California firstOrange County, LA and San Diego, then outward where the business warrants it.
- Situation
- Founder-ownedSuccession, retirement, or an owner who wants out of the day-to-day but not out of the story.
- Also
- Multi-site platformsFragmented, multi-location businesses with three or more locations and a model that repeats.
- Not for us
- Turnarounds, or one big customerI do not buy broken companies to fix them. I do not buy a business where one customer is more than a fifth of revenue. And I do not buy anything in tire or automotive services.
Who I am
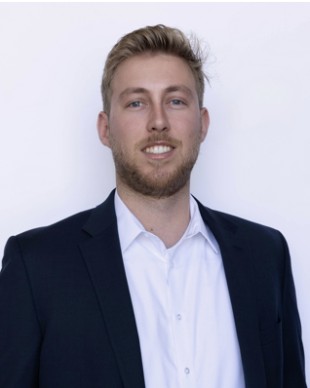
Kenneth Pettibone
Principal, Stillwater Partners
I have spent the last five years buying companies for private-equity-backed platforms. Every one of them ran between $2.5M and $16M in revenue — the size where the owner still knows every employee by name. Nine closed, seventeen locations in all, across industrial manufacturing and multi-site services.
What that mostly taught me is how often a good company gets handed to the wrong buyer. Stillwater is the answer to that. It exists to buy a small number of very good businesses and keep them — no fund, no clock, no obligation to flip a company because a fund's life ran out.
I have also owned and run sheet metal and welding shops. Being on the floor taught me the difference between owning a business and running one, and it is why I have no intention of running yours. The people who already know your company will keep operating it. My job is capital, structure and stewardship of what works.
My family has been in Orange County since 1962. I am not moving your business, and I am not going anywhere.
How the money works
There is no fund behind me. That is deliberate.
A fund buys with money it raised years ago, on terms it already promised its own investors. That is convenient for the fund. It is not always what is best for the company the fund buys.
Stillwater finances each acquisition on its own. Nothing is committed in advance, so the capital for your business gets competed for rather than assumed — senior debt, mezzanine, outside equity, seller financing, in whatever combination the company can comfortably carry. I am not tied to any one lender or investor, which means the structure gets built around your business instead of around someone's return math.
The honest trade is that this is slower than writing a check out of a fund. That is also exactly why there is no deployment pressure, no committee forcing a bid, and no pre-set date when someone else decides your company gets sold.
What I owe you: before you sign a letter of intent, you will know how the transaction is financed, who the capital is coming from, and what has to be true for it to close. If I cannot answer that to your satisfaction, you should not sign it.
How this goes
Four steps, and you can stop at any one of them.
- A conversation, under NDA if you want one first. No financials required. I want to understand the business, what you want to happen to it, and whether I am even the right kind of buyer.
- You send financials. I read them myself. You get a straight answer: a valuation range and how I got there, or a no with the reason. Not a maybe.
- A letter of intent that reflects the conversation we actually had. Structure, terms, your role afterward, what happens to your team — written down before anyone spends money on lawyers.
- Diligence to confirm, then close. I confirm what you told me. I do not re-trade a price because I found something I could have asked about earlier.
Working together
Intermediaries, operators and advisors.
For brokers and bankers
Every teaser is read by the principal — the same person who will be on the call, at the closing table, and answering the phone two years later. You get a real answer either way, not silence.
The box is above and it is real: $2M+ of current EBITDA, industrial, B2B or a simple well-run service business, founder-owned, Southern California first. Nothing in tire or automotive services, ever, and nothing where one customer is more than a fifth of revenue.
For operators and advisors
I am building a bench of people to think with — operators who have run something, industry hands who know a market cold, and finance people whose judgment is worth a phone call on a Sunday.
If you have run a business and would consider leading or chairing one again, or you simply like looking at deals, I would rather know you before there is a deal on the table.
Contact
If you are even thinking about it, start with a conversation.
There is no pitch and no obligation. Plenty of these conversations end with “not yet” — that is a perfectly good outcome, and I will still be here when the timing changes.